Turkey Bank Deposit Interest 2026: Rates, Tax and Real Return
What do Turkish banks pay on deposits in November 2026? Lira and dollar rates, the 17.5% withholding tax, deposit insurance and the real return after inflation.
Bank interest in Turkey in November 2026 is roughly 32% to 39% a year (gross) on a one-month lira deposit, depending on the bank, and usually under 2% on a dollar deposit. The bank withholds 17.5% tax from lira deposit interest, and annual inflation in Turkey is 29.77%. So the real return is far lower than the figure on the bank's board. This guide covers today's rates, the tax, deposit insurance, account opening for Iranians and a simple real-return calculation.
Most Persian articles on this subject still quote 45% or 50% interest. Those figures belong to earlier years. Turkey's central bank has cut its policy rate several times since 2025, and deposit rates have followed it down.
What are bank interest rates in Turkey today?
Every rate starts from the policy rate of the Central Bank of the Republic of Türkiye (TCMB). On 22 October 2026 the Monetary Policy Committee cut it from 37% to 36%. Banks usually set deposit rates slightly below or close to this level.
According to central bank weekly data reported by Bloomberg HT, the average one-to-three-month lira deposit rate fell to 36.4% in the week of 9 October 2026. That is the lowest level since 2023. At the start of 2025 the same average was about 50%.
The table below shows 32-day lira deposit rates at several large banks. The figures come from the banks' official pages on 3 November 2026, as compiled by the daily Takvim.
| Bank | Gross annual rate | Net interest on 1 million lira for 32 days | Condition |
|---|---|---|---|
| Akbank Mobile | 39% | 28,208 lira | New mobile customers only, 500,000 to 10 million lira |
| Garanti BBVA | Up to 38% | Up to 27,485 lira | Rate depends on the customer |
| Enpara | 36.75% | 26,581 lira | 750,000 to 1.5 million lira |
| İş Bankası | 36.75% | 26,581 lira | Customers with no existing term deposit |
| Halkbank | 35% | 25,315 lira | 500,000 to 1 million lira |
| Ziraat | 32% | 23,145 lira | Online deposit, from 500,000 lira |
Two points about this table:
- The highest rates are usually campaigns. They apply to new money, new customers or the mobile channel, and may drop after the first maturity.
- Rates change every week. Check the rate in the bank's own app before you deposit, not in an article.
Tax on deposit interest in Turkey (stopaj)
In Turkey the bank deducts tax on deposit interest when it pays the interest. This deduction is called stopaj. You do not file a separate return for it. The rates were raised by a presidential decision published in the Official Gazette on 9 July 2025 and stand as follows in 2026:
| Deposit type | Tax rate |
|---|---|
| Lira, up to 6 months (including 32-day) | 17.5% |
| Lira, 6 months to 1 year | 15% |
| Lira, over 1 year | 10% |
| Dollar, euro and other currencies | 25% |
Example: one million lira at 39% for 32 days earns about 34,192 lira gross. After the 17.5% deduction, about 28,208 lira reaches your account.
Real return: after inflation and the dollar rate
The main question for Iranian savers is how much they earned in dollars in the end. Two figures matter:
- Inflation: According to the Turkish Statistical Institute (TÜİK), annual inflation in October 2026 was 29.77%.
- The dollar rate: The dollar was about 42.2 lira in early November 2025 and about 50.15 lira on 6 November 2026. In one year the dollar rose about 19% against the lira.
If you renew a 32-day deposit every month at about 36%, the net annual return after tax is about 30%. The result in dollars depends on how much the dollar rises over the same year. The table below is a hypothetical calculation, not a forecast:
| Rise in the dollar rate over one year | Result of a 30% deposit in dollars |
|---|---|
| 10% | About 18% gain |
| 20% | About 8% gain |
| 30% | Roughly break-even |
| 40% | About 7% loss |
Put simply, a lira deposit only earns in dollar terms when the lira loses value more slowly than the interest rate. The central bank is cutting rates, so future deposits will probably pay less than today's rates. A currency shock can also wipe out several months of interest in a few days.
Dollar and euro deposits in Turkish banks
A foreign-currency deposit carries no lira risk, but it pays very little. Dollar deposit rates in 2026 have been reported between zero and about 2% at most banks, usually negotiated and dependent on the amount. A 25% tax is deducted even from this small interest.
The FX-protected deposit scheme (KKM) no longer exists either. New accounts stopped in August 2025, and its balance reached zero in August 2026. Any site still offering KKM has outdated information.
Deposit insurance: how much of your money is guaranteed?
Turkey's Savings Deposit Insurance Fund (TMSF) guarantees individuals' deposits up to a set limit if a bank fails. From 1 January 2026 the limit rose from 950,000 to 1,200,000 lira. At the 6 November 2026 rate this is about 24,000 dollars.
- The limit applies per person per bank. Several accounts at one bank, or at different branches of the same bank, are added together.
- Foreign-currency deposits are covered too, but the limit is calculated and paid in lira.
- Only deposits at branches inside Turkey are covered.
If you hold a large amount, splitting it across several banks reduces the risk.
Can Iranians open a deposit account in Turkey?
Yes, but not every bank or branch opens accounts for Iranians. The decision depends on the bank's internal policy and even on the branch. On 4 September 2026 the US Treasury sanctioned an Istanbul-based investment bank for allegedly serving Iranian financial institutions. After events like this, banks become stricter about the source of Iranian customers' funds. Iranian bank cards also do not work in Turkey.
The usual steps to make a deposit:
- Get a tax number. A tax number (vergi numarası) is required by almost every bank. See the full guide in Tax number in Turkey.
- Have a Turkish SIM card. The bank's one-time passwords arrive by text message.
- Prepare your documents. Passport, an address in Turkey and, at many branches, a residence permit card.
- Document the source of funds. Large transfers require proof of where the money came from.
- Open the account and create the deposit in the bank's app. The app rate is sometimes higher than the branch rate.
More detail, including the banks that usually work with Iranians, is in our guide to opening a bank account in Turkey.
Bank deposits for Turkish citizenship
One of the investment routes to Turkish citizenship is depositing at least 500,000 dollars or its equivalent in banks recognised by the Banking Regulation and Supervision Agency (BDDK) and keeping it for 3 years. This condition is set out in Article 20 of the regulation implementing the Turkish Citizenship Law. Under the 2022 amendment, the foreign currency must be sold to the central bank through the bank and the lira equivalent deposited. So on this route your money is in lira for those three years, and you carry the currency risk.
The alternative route is buying property worth at least 400,000 dollars. We explain its conditions in Turkish passport by property investment. These rules can change. Check the current conditions with ALO TURKEY's consultants before any decision.
Bank deposit or property?
Many of our clients are torn between a lira deposit and buying a flat in Istanbul. Each has its use:
| Criterion | Lira deposit | Property in Istanbul |
|---|---|---|
| Currency risk | Full; the money is in lira | Lower; property prices usually move with inflation and the dollar |
| Liquidity | High; released at maturity | Low; a sale can take months |
| Regular income | Monthly interest, with 17.5% tax | Monthly rent |
| Entry cost | Almost zero | Title deed transfer tax, commission and other costs |
| Residence | None | A qualifying property can provide residence |
| Citizenship | 500,000 dollars, 3 years | 400,000 dollars, 3 years |
For money you will need within a year, a short-term deposit makes more sense. For multi-year capital whose dollar value you want to protect, property is the more serious option. You can work out the buying costs with the Turkey property buying cost calculator. On rental income, read Rental income in Istanbul and Is property investment in Turkey still profitable?.
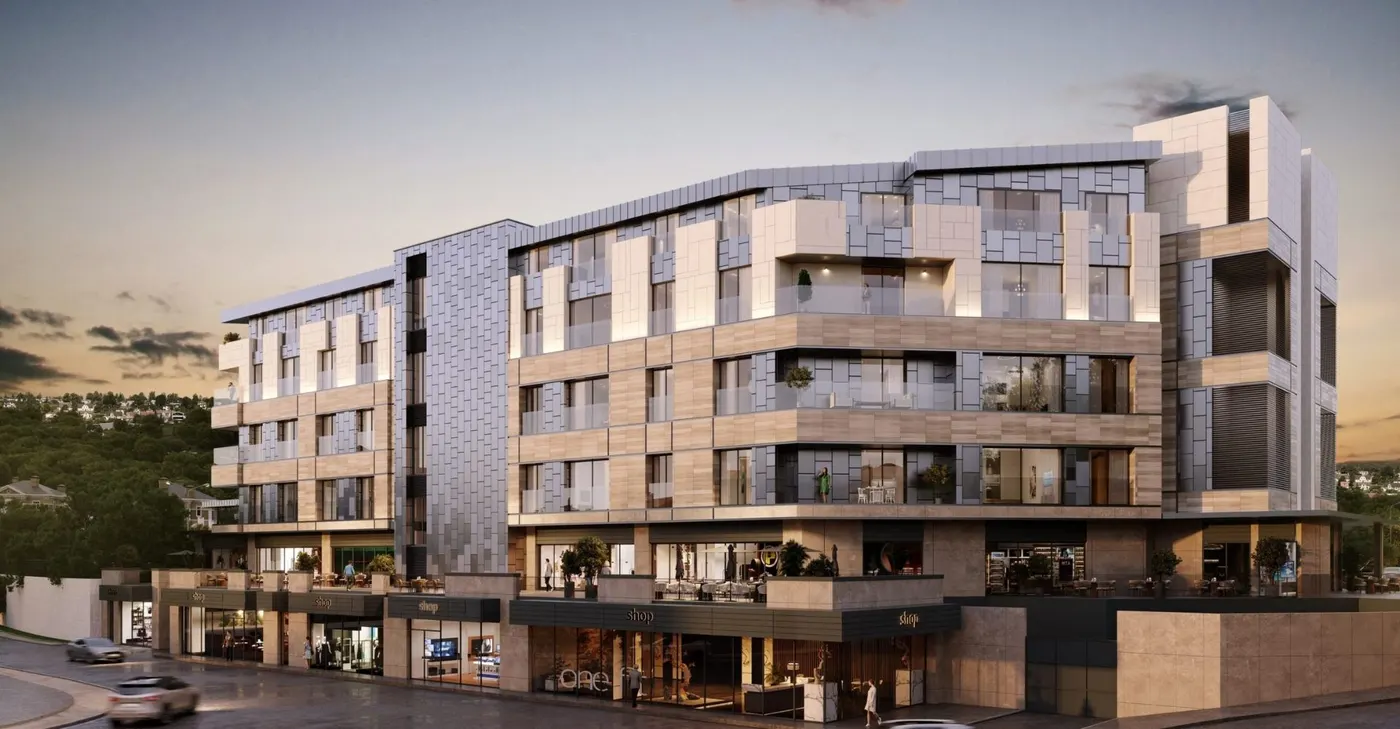
If you are considering property in the prime northern districts of Istanbul, the Seba Center project in İstinye is one example from our listings.
Frequently asked questions
Is bank interest in Turkey paid monthly?
On a 32-day deposit, interest is paid at the end of each term, and you can withdraw it or redeposit it with the principal. On longer deposits, interest is usually paid at maturity.
Do foreigners also pay tax on deposit interest?
Yes. The bank deducts the tax from every depositor when it pays the interest: 17.5% on lira deposits of up to 6 months and 25% on foreign-currency deposits.
What is the minimum deposit?
Each bank sets its own minimum. The highest rates are usually for amounts of 500,000 lira and above.
What happens if the bank fails?
TMSF pays up to 1,200,000 lira per person per bank. Any amount above this limit is not guaranteed.
Can I open a deposit without a residence permit?
Some branches open accounts with a passport and tax number, but many ask for a residence permit card. For Iranians this depends on the bank and the branch.
Free consultation with ALO TURKEY
ALO TURKEY's team in Istanbul helps Persian-speaking investors choose well between deposits, property and the residence and citizenship routes. We support you with the tax number, opening an account and choosing the right property. Turkish tax and banking rules change often, so speak with our consultants before you decide. Contact us on WhatsApp or through our contact page.
Sources: Central Bank of the Republic of Türkiye (TCMB, rate decision of 22 October 2026), Turkish Statistical Institute (TÜİK, October 2026 inflation), Official Gazette of Türkiye (withholding tax decision, 9 July 2025), Savings Deposit Insurance Fund (TMSF, 2026 limit), regulation implementing the Turkish Citizenship Law, Takvim (bank rates, 3 November 2026), Bloomberg HT (average deposit rate and dollar rate, October and November 2026), US Department of the Treasury (4 September 2026).